

Wall Street faces the test of evidence. Perspective for S&P 500, Nasdaq 100 and Dow Jones on 2 November 2026

BY
Ben Graham
|

By using this site, you agree to our Terms of Use of Use and Privacy Policy
October's tech rout, a re-rating of AI prospects, and tomorrow's US congressional elections keep equity markets on edge. The October FOMC, where two votes favored an immediate hike, heightened concerns about further tightening in December. Capital continues to flow out of an overheated Nasdaq and into value sectors, widening the historical divergence between indices.
Key facts:
Trading focus:
Fundamental outlook for US indices this week
The primary political trigger is the congressional vote. Historically, election outcomes have direct implications for tax policy, tariffs, and the fiscal stance. Ahead of the count, large funds typically de-risk and adopt a wait-and-see stance. Meanwhile, the 10-year Treasury yield has fallen to about 4.93% amid a rush into safe-haven bonds, but equities are not responding with the usual optimism — bond flows are being read as a sign of slowing growth momentum.
At the micro level, Q3 earnings season has exposed investor fatigue with hefty AI spending. The one-day collapses in Alphabet (-12.6%) and Intel (-28.6%) demonstrated that the market no longer forgives multibillion-dollar capex without commensurate free-cash-flow payoff. Money is not leaving the market entirely — it is rotating: the equal-weighted S&P 500 and the conservative Dow Jones are outperforming mega-caps as institutions favor defensive healthcare, retail, and commodity leaders.
Trading plans for this week
S&P 500 (US 500)
External calm in the S&P 500 is deceptive: while the index hovers near record highs, an internal sell-off is well underway. The Kobeissi Letter estimates that more than 60% of S&P 500 constituents have fallen at least 20% from their peaks — technically, a bear market for the majority of US stocks, even as the cap-weighted index gives an illusion of stability.
The cause is the extreme concentration of capital. Roughly 70% of the rally from March lows rested on just ten companies. That foundation is rapidly deteriorating: four of the Magnificent Seven have lost 15% or more of market cap, and the mega-cap group has wiped out about $4 trillion in value, exceeding the entire crypto industry. Alphabet shares plunged by 31% from $400 to $282, and Meta is down more than 21% from August highs.
Tech favorites and crypto-linked names are at the epicenter of liquidation:
The Kobeissi Letter calls this a harsh reality: the outright majority of S&P 500 components are already in bear territory. Analysts stop short of forecasting a systemic market collapse. This anomaly could turn into an attractive entry point if money rotates broadly and liquidity flows into lagging sectors.
The index finished last week near 7,580, about 3% off October highs. We expect volatile trading within a wide corridor. Primary scenario (short positions from the upper boundary):
Alternative scenario (buy from support):
Nasdaq 100 (US Tech 100)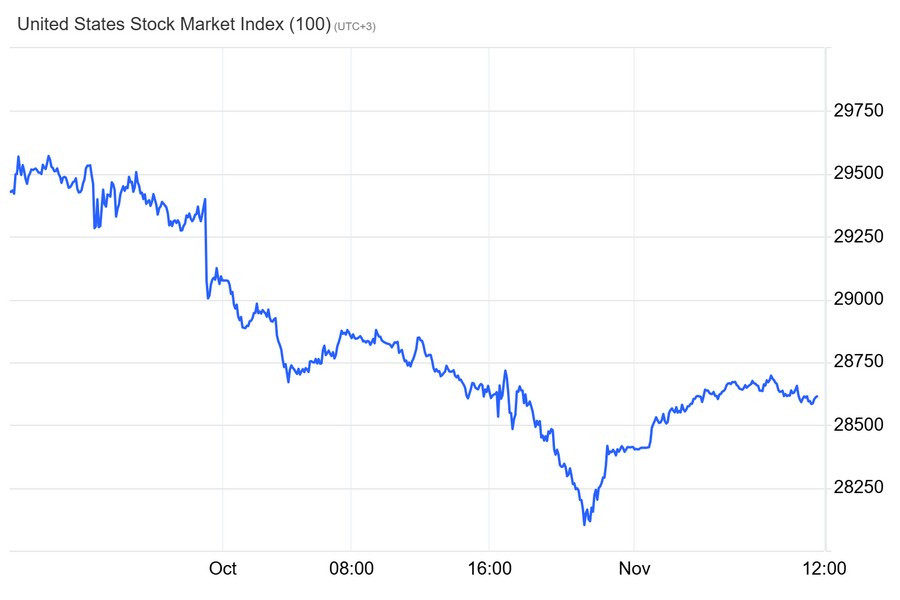
The index is trading around 25,400. The technical picture remains dominated by semiconductor selling. Rallies are used by large players to lock in gains. Primary scenario (sell on corrections):
Short-cover cancellation scenario: consolidation above 26,150 would invalidate the bearish wave and open a path toward testing 26,500.
Dow Jones (US 30)
The index closed October near 51,770 and remains relatively resilient thanks to rotation into real-economy sectors. Primary scenario (buy the dip):
Alternative scenario (sell a downside breakout):
US midterm days always bring sharp volatility and emotional repricing. Given the painful rebalancing in the tech sector and the Fed's open door for a December rate hike, speculative rushes can be costly. Key advice for the coming sessions: do not trade ahead of political news, stick to pre-defined risk levels, avoid moving stop-loss orders against positions, and wait for volume confirmation after election results.
Cold decisions, iron discipline, and a profitable trading week! "We don't have to be smarter than the rest. We have to be more disciplined than the rest," Warren Buffett said.